A note on timing. This post covers 2023, and it’s reaching you late. We’re catching up on the annual budgets after a multi-year gap. The 2024, 2025, and 2026 annuals will follow.
If 2022 was the proof of our return to travel, 2023 was the year we showed it wasn’t a fluke. We spent $57,228. That’s essentially flat vs 2022, down $211 (0.4%). After a 12% jump in 2022, holding steady felt like a win.
And what a year it was. Jenni and I got engaged! We spent 46 days in Europe in the spring for under $7,000. Then another 30 days in Portugal, Spain, and the Azores in the fall for $4,500. That’s 76 days in Europe all told. A surprise dental bill kicked off January. And through it all, we saved a net 52% of our new income.
Each year, Jenni and I break down our annual expenses to compare our current selves to our past. We want to see if we’re sticking with our spending trends over time. The expense data forms our annual FIRE budget basis.
Our life feels pretty “normal”, despite the FIRE mindset. We eat out on occasion, travel plenty, and can’t quite avoid some of the world’s latest tech gadgets. Two cars and a house in walkable central Virginia. Seemingly modern lives with all the creature comforts one might desire.
We hope revealing the details of our spending in this FIRE budget will inform your own spending goals. Perhaps it will lead you to a few tricks for how we keep our spending low and spend less than we earn.
While this post doesn’t include information on monthly income or net worth changes, our monthly budget updates do (since May of 2020!). You can dig into the numeric details of how we’ve reached FIRE through those budget reports.
Why have a FIRE Budget?
Jenni and I started tracking our combined expenses as a couple in 2016. By doing so, we can monitor for developing trends. If our combined restaurant expenses are on the rise, it might be indicative of a problem we need to address. But the data can also be reassuring. We walk through all these categorical spending details below. We hope you find some diamonds in the rough to help build your sustainable FIRE budget.
What changed in 2023
- Spending was flat. $57,228 vs $57,439 in 2022. Down 0.4%. After a 12% jump the year before, we held the line.
- We got engaged. The August engagement cost $2,535. It sits in its own One-Time Expenses line in the table below, pulled out of Gifts & Donations so the years compare cleanly. The rings were a small part of that. The celebration was the rest.
- A dental surprise kicked off the year. January brought nearly $2,000 in dental expenses. Health & Fitness rose 31% on the year.
- Travel cost less while we traveled more. 46 days in Europe in the spring plus 30 days in Portugal, Spain, and the Azores in the fall, and Travel still fell 26%. Rewards points and certificates made that possible.
- We cooked more and ate out less. Groceries rose 41%. Restaurants fell 37%. More time in Airbnbs changed the mix.
2023 FIRE Budget
Before we get into the nitty-gritty, here’s the 50,000-foot view. This table shows each parent category for 2023 next to 2022, so you can see what moved.
| Category | 2022 | 2023 | Change |
|---|---|---|---|
| Home (incl. property tax) | $20,505.35 | $20,107.62 | −1.9% |
| Food & Dining | $7,944.09 | $8,300.08 | +4.5% |
| Travel | $13,283.94 | $9,795.36 | −26.3% |
| Health & Fitness | $5,609.45 | $7,343.80 | +30.9% |
| Bills & Utilities | $1,526.81 | $1,553.96 | +1.8% |
| Auto & Transport | $3,413.25 | $3,022.00 | −11.5% |
| Entertainment | $887.17 | $954.43 | +7.6% |
| Shopping | $387.23 | $1,851.39 | +378%* |
| Gifts & Donations | $822.39 | $1,175.63 | +43.0% |
| Personal Care | $178.88 | $150.23 | −16.0% |
| Fees & Charges | $30.00 | $252.50 | +742% |
| Education | — | $125.00 | new |
| Business Services | — | $60.66 | new |
| One-Time Expenses† | $2,850.00 | $2,535.00 | −11.1% |
| Total spending | $57,438.56 | $57,227.66 | −0.4% |
* Shopping: read the footnote before taking +378% at face value. Our tracking changed. In 2022, reselling electronics netted against the Shopping category (a $101 profit). In 2023, sales went into a separate Local Sales income category ($800) that doesn’t net against specific spending. So an item bought then sold shows as spend plus income, never connected. The jump is real, but it’s overstated by that shift. See the Shopping note below.
† One-Time Expenses pull one-off items out of their parent categories so the years compare cleanly. 2022 is the Prius upgrade ($1,000) plus the HOA garage assessment ($1,850). 2023 is the engagement ($2,535), moved out of Gifts & Donations. The totals are unchanged.
A note on how this table is built: we kept the 2022 presentation so the years compare cleanly. Property tax sits under Home (as in 2022), not in its own Taxes line. Personal Care is its own line (as in 2022), not folded into Shopping. The 2023 monthly posts group those items differently, so the full subcategory table below carries a footnote on the regrouping.
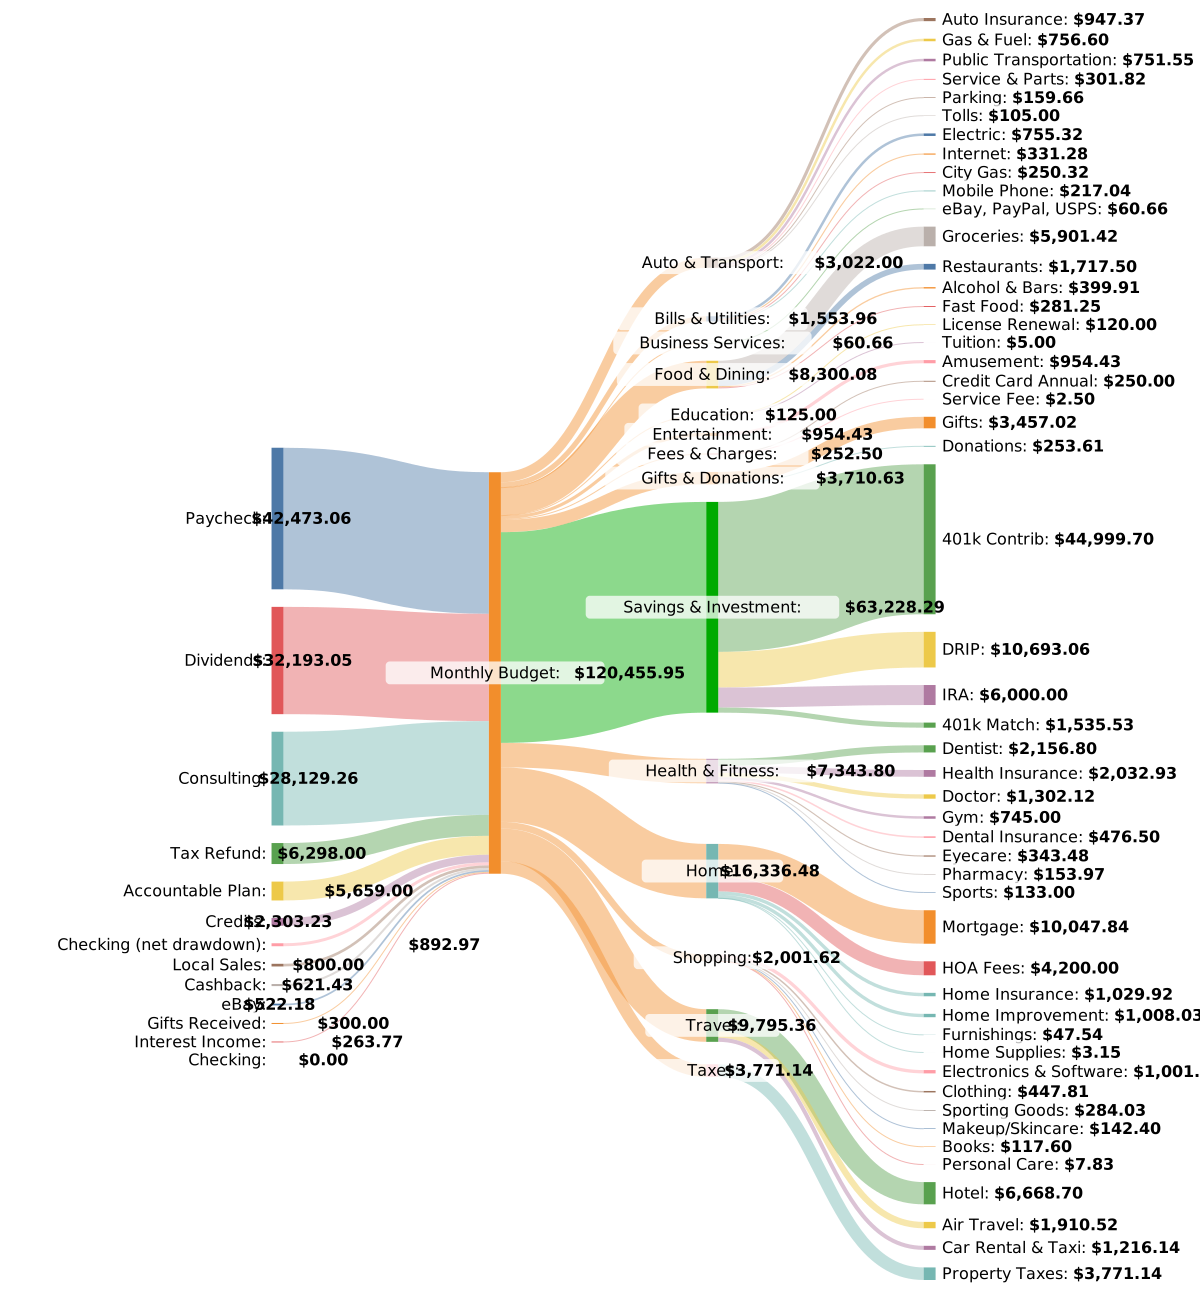
The Sankey tells the same story as the table, visually. Paycheck, dividends, and consulting are the big income sources on the left. Home, Food & Dining, and Travel dominate the spending on the right. And the thick band into Savings & Investment is the year’s saving.
Expense details
As a point of reference, we live in a medium-cost-of-living, medium-sized city in Virginia, in the United States. We live on the edges of a city proper so we generally walk to entertainment, parks, and stores. Despite the higher taxes and living costs, we figured that free entertainment, easy walking, and reduced commuting made city life a better choice for us than country living.
The full subcategory table is long, so it sits collapsed below. Tap or click to expand it. The parent totals are what most readers compare; the subcategories are the receipts.
The table is grouped by parent categories (leftmost column), subcategories within that parent (middle column), and the amount spent (right column). Parent categories are totaled on their row, summing all of the subcategory expenses below it.
Categorized expense table: full subcategories (tap or click to expand)
| Category | Subcategory | Spent ($) |
|---|---|---|
| Home | 20,107.62 | |
| Mortgage | 10,047.84 | |
| Property Tax | 3,771.14 | |
| HOA Fees | 4,200.00 | |
| Home Insurance | 1,029.92 | |
| Home Improvement | 1,008.03 | |
| Furnishings | 47.54 | |
| Home Supplies | 3.15 | |
| Food & Dining | 8,300.08 | |
| Groceries | 5,901.42 | |
| Restaurants | 1,717.50 | |
| Alcohol & Bars | 399.91 | |
| Fast Food | 281.25 | |
| Travel | 9,795.36 | |
| Hotel | 6,668.70 | |
| Air Travel | 1,910.52 | |
| Car Rental & Taxi | 1,216.14 | |
| Health & Fitness | 7,343.80 | |
| Dentist | 2,156.80 | |
| Health Insurance | 2,032.93 | |
| Doctor | 1,302.12 | |
| Gym | 745.00 | |
| Dental Insurance | 476.50 | |
| Eyecare | 343.48 | |
| Pharmacy | 153.97 | |
| Sports | 133.00 | |
| Bills & Utilities | 1,553.96 | |
| Electric | 755.32 | |
| Internet | 331.28 | |
| City Gas | 250.32 | |
| Mobile Phone | 217.04 | |
| Auto & Transport | 3,022.00 | |
| Auto Insurance | 947.37 | |
| Gas & Fuel | 756.60 | |
| Public Transportation | 751.55 | |
| Service & Parts | 301.82 | |
| Parking | 159.66 | |
| Tolls | 105.00 | |
| Entertainment | 954.43 | |
| Amusement | 954.43 | |
| Shopping | 1,851.39 | |
| Electronics & Software | 1,001.95 | |
| Clothing | 447.81 | |
| Sporting Goods | 284.03 | |
| Books | 117.60 | |
| Gifts & Donations | 3,710.63 | |
| Gifts | 3,457.02 | |
| Donations | 253.61 | |
| Personal Care | 150.23 | |
| Makeup/Skincare | 142.40 | |
| Personal Care | 7.83 | |
| Fees & Charges | 252.50 | |
| Credit Card Annual | 250.00 | |
| Service Fee | 2.50 | |
| Education | 125.00 | |
| License Renewal | 120.00 | |
| Tuition | 5.00 | |
| Business Services | 60.66 | |
| eBay, PayPal, USPS | 60.66 | |
| One-Time Expenses¹ | ||
| Engagement (Aug) — see below | 2,535.00 | |
| Subtotal² | 47,179.82 | |
| GRAND TOTAL | 57,227.66 | |
| 4% SWR Basis³ | 1,430,691.50 |
Footnotes:
(1) Large, unplanned, and unbudgeted expenses can come up but should be infrequent. The engagement is already counted in Gifts & Donations above. We call it out here because it’s one-time and lumpy, not because it’s additional.
(2) Defined as all expenses minus mortgage principal & interest. If we paid the mortgage off, this is what we’d have spent. The mortgage is reported as a single payment line in 2023 ($10,047.84); 2022 split it into principal ($4,720.24) and interest ($5,327.60).
(3) To maintain this level of spending, we’d need this much in appreciating assets to meet the classic “4% rule” (25× our annual expenses, the Grand Total number).
A regrouping note: the 2023 monthly posts put property tax in its own Taxes category ($3,771.14) and fold Makeup/Skincare and Personal Care into Shopping. We’ve moved property tax back under Home and split Personal Care out, to match the 2022 layout. And 2022’s Home Improvement ($1,152) and Service ($1,152) were budget accruals: 1% of dwelling value, set aside each month. The 2023 Home Improvement figure ($1,008.03) is actual spend, not an accrual. Don’t compare those two as if both were actuals.
FIRE budget breakdown
We think that the expense numbers only tell half the story. For each spending category, we explain what expenses we incurred, why, and some spending strategies to help you manage your costs. If you’re uninterested in the details, skip down to our 2016–2023 FIRE Budget.
Home
Mortgage flat, insurance up, and one big repair.
- Mortgage ($10,048) and property taxes ($3,771). Our mortgage payment didn’t change for the year, principal and interest combined. We’re happy to have a low-interest mortgage right now. Property taxes stayed in line with prior years.
- Home insurance ($1,030). Rose about 27% over 2022’s $812. Our coverage is enough to cover replacement costs and has a high deductible scheme. We earn a slight discount by being shareholders of Berkshire Hathaway (and therein, Geico).
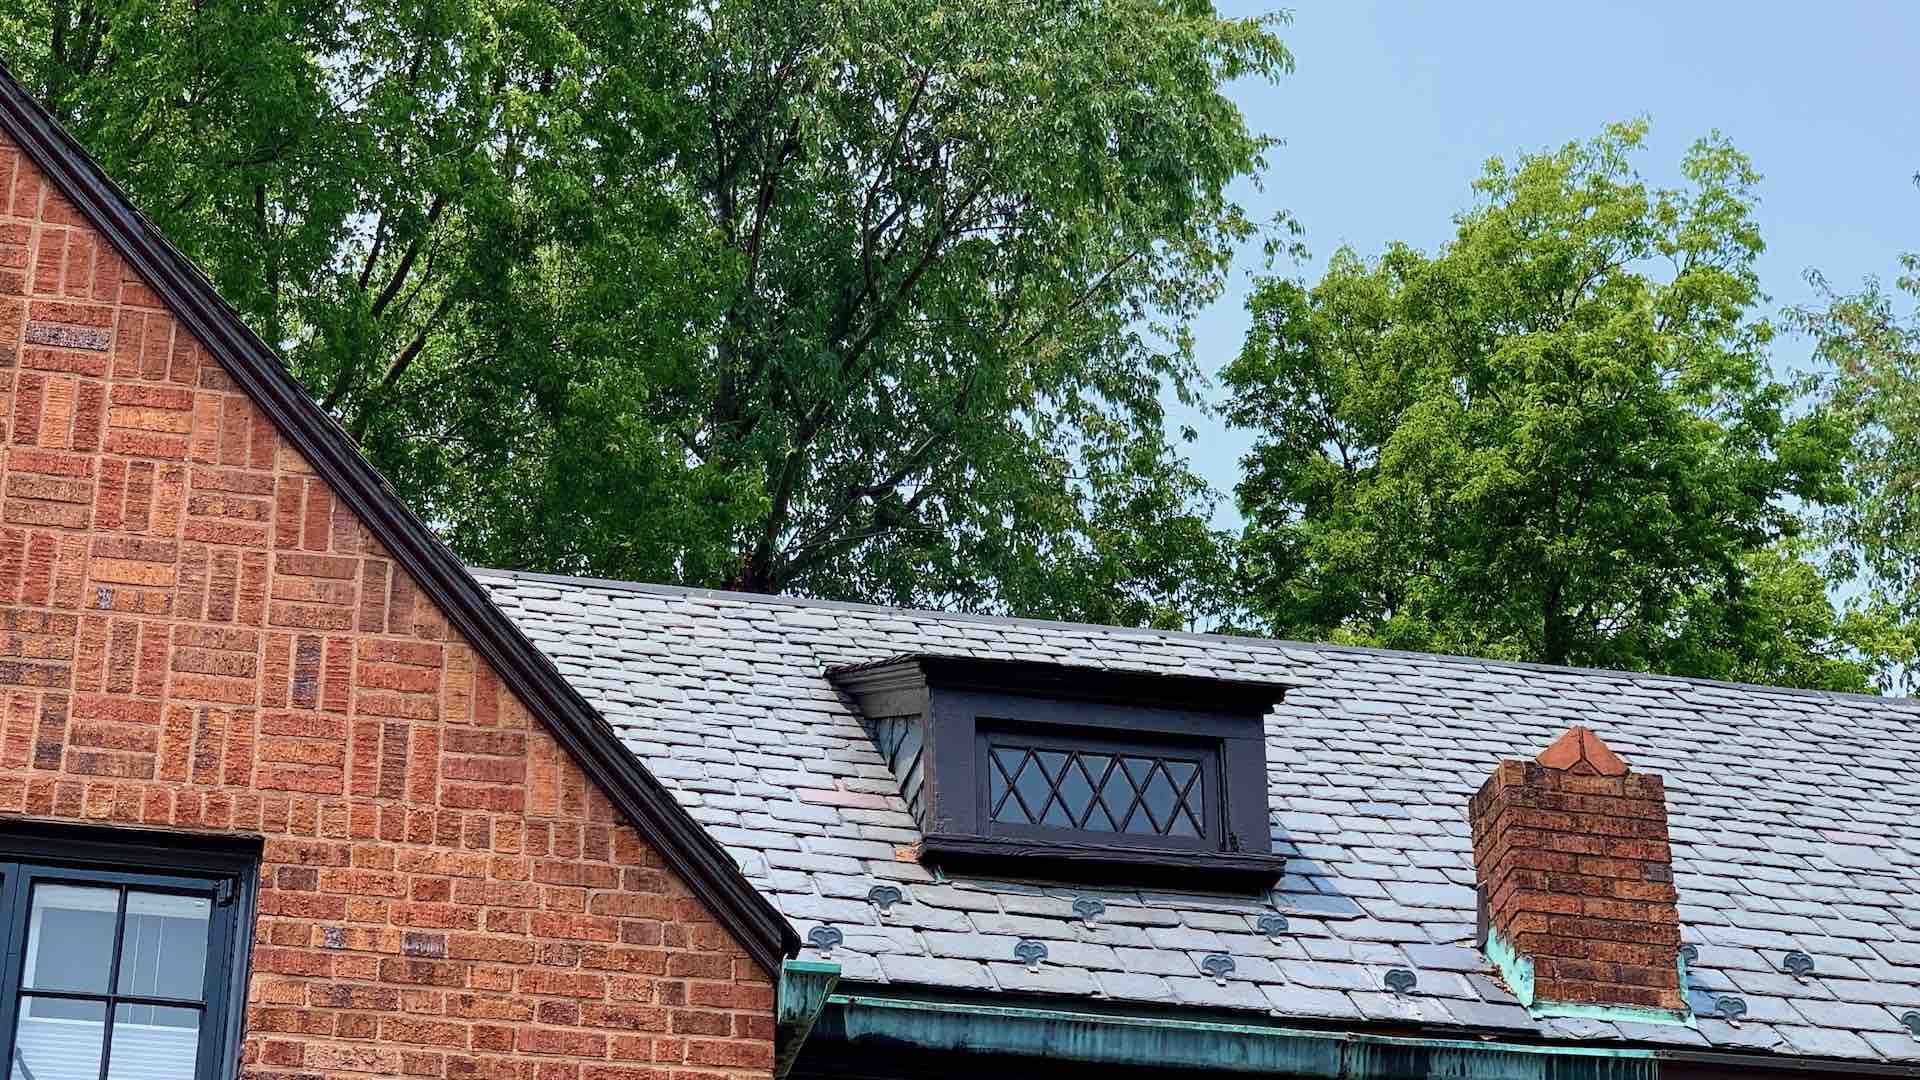
- Home improvement ($1,008). Actual spend this year, not an accrual. The big item was an attic window sash repair in June ($989.59). The paint was peeling and the wood framing had weakened. We finally tackled it.
- HOA fee ($4,200). It may seem high at first glance, but the fee covers multiple utility-like expenses: heating, water usage, landscaping, common area maintenance, garage maintenance, and gutter cleaning. Our HOA is managed internally by fellow owners, unpaid. Our neighborhood was originally set up as a cooperative in the 1920s.
Food & Dining
We cooked more and ate out less.
- Groceries ($5,901). Jumped by 41% over the year. This is the category where our travel style showed up most clearly. We spent 76 days in Europe, mostly in Airbnbs, and we cooked most of our meals there.
- Restaurants ($1,718). Fell 37% over 2022 levels. That’s the swap: more groceries, fewer restaurants.
- How we eat. We try to be flexible with our diets while maintaining a healthy, mostly pescatarian, mix of foods. And we do our best to abide by the principles outlined in our expert how to save money on groceries post. A pretty typical meal out for us in Portugal ran about $11 per person, drinks included. Not bad.
Travel
2023 kept us moving, but for less money.
- The trips. A missed flight to Madeira in March, 46 days in Europe across April and May (Portugal, Spain, Netherlands), 30 days in Portugal, Spain, and the Azores across September and October, fall trips to Cancún and Nashville in November, and a desert holiday in Phoenix in December. We stayed busy throughout the year.
- Hotels ($6,669). The largest chunk of our travel costs, about two-thirds of it. We’ve got to have somewhere to rest our weary legs at the end of the day. We cut this cost dramatically through the use of hotel certificates and travel rewards. We detail how in our May budget update.
- Flights ($1,911). Less than half of 2022’s $4,057. Rewards points and miles did the work. Through the smart use of rewards points and certificates, we cut our 46 days in Europe from about $15,000 to under $7,000. That brought the trip down to about $67 per person per day.
- Rental cars and taxis ($1,216). Slightly down from 2022 ($1,280). We rented cars to tour Portugal and Spain, and the Azores needed one too.

Health & Fitness
A dental surprise drove the year, but insurance and pharmacy fell.
- Dentist ($2,157). January set the tone. We opened the year with nearly $2,000 in dental expenses. The endodontist quoted $3,585 for the work, plus $185 for a scan. We wrote about how we cut that bill roughly in half in our dental post. Dentist costs for the year came to $2,157, vs $259 in 2022.
- Doctor ($1,302). Up from $706, with copays for multiple visits to various specialty doctors.
- Health insurance ($2,033). Fell from $3,302. Our income dropped, so our ACA rates dropped, which we both use.
- Pharmacy ($154) and gym ($745). Pharmacy costs collapsed from $625, mostly Jenni’s monthly generic medication costs coming down. Gym costs cover our rock climbing gym membership and fitness classes.
Health & fitness is no longer the great expense concern it once was. Even if the ACA is significantly changed in the future, we’re getting more familiar with international care and other solutions.
Bills & Utilities
Home less this year, so utilities barely moved.
- Utilities. Our utilities bill is about three-quarters electricity. The remainder is city gas. Other standard utilities (heating, water, trash, etc.) are covered by our HOA fee. As we were home less this year, this expense category barely moved, up just 1.8% to $1,554.
- Mobile phone ($217). Covers our two prepaid SIM cards. We both have modern unlocked iPhones so we can use secondary cell provider services.
- Internet ($331). Provided by Comcast. The service is rarely down and not too expensive if you’re willing to call in to negotiate once a year.
Auto & Transport
Little commuting, more European transit.
- Commuting and gas ($757). Neither of us does much commuting these days. The few days per week Jenni still works at the pharmacy, it’s a short 2–3 miles each way. My work is all remote. Our gas & fuel expenses come mostly from trips where we rent a vehicle to tour the area.
- Auto insurance ($947). Provided by Geico, with a shareholder discount and a multi-line discount since our home insurance is through them as well.
- Public transportation ($752). More than doubled from $316 in 2022. That’s the Europe metros, subways, and trains.
- Service & parts ($302). Covered routine vehicle maintenance and inspection. No catalytic converter drama this year.
Entertainment
Museums, parks, and big hikes across 76 days in Europe.
- Amusement ($954). Covers the museums, parks, holiday events, and architectural wonders we visited while traveling. There were countless of them across 76 days in Europe.
- The highlights. Kayak tours, train shows, big hikes. The same pattern as 2022, just a little more of it.
Shopping
Electronics drove the jump, and a tracking change overstated it.
- Electronics & software ($1,002). The line that moved most. In 2022, this category was a small profit center for us (−$101). We bought used gear and resold old items for more than we paid. In 2023, we bought about $1,000 of gear and the reselling didn’t net the same way.
- A tracking change, not a spending change. In 2022, sales netted against the Shopping category. In 2023, sales went into a separate Local Sales income category ($800) that doesn’t net against specific spending. So the +378% jump overstates the real change.
- The rest. Clothing ($448) came from travel upgrades, mostly quick-drying pants and shirts. Sporting goods ($284) covered a few small upgrades. Books ($118) round it out.
Gifts & Donations
The engagement is the gift giving this year.
- Gifts ($3,457). The engagement. We’ll say more about that in the One-Time Expenses section below. Outside the engagement, gift giving reflects pretty typical holiday or birthday-related exchanges.
- Donations ($254). Down from $605 in 2022. We focus on local organizations and helping those we know. We report most of it in our monthly budgets. The figure above does not include our DAF giving as part of our reader fund.
Personal Care
Restocking, and down from $179.
- Personal care ($150). Reflects restocking makeup, sunscreen, and other personal care products. We handle our own haircuts and grooming. Down from $179 in 2022.
Fees & Charges
Bank fees are gone.
- Amex Gold ($250). The $250 here is the Amex Gold annual fee.
- It nearly pays for itself. The card gives $10 a month in Uber Eats credit and $10 a month in Grubhub credit, $240 a year, plus other statement credits. Chris renewed it for the benefits but might skip it next year. One card, one fee, vs $30 in 2022.
Education and Business Services
Two new lines this year.
- Education ($125). Mostly a license renewal ($120).
- Business Services ($61). eBay, PayPal, and USPS fees from reselling.
One-Time Expenses
Occasionally, very large expenses pop up that are once in a lifetime or decade events. A down payment on a house, an RV to go camping in, or a new car are good examples. We had one of these this year. And it’s the best one yet.
The engagement: $2,535. Yes, we’re engaged. August was the month. The $2,535 is what hit our August Gifts line. It’s the full engagement, not just the ring. The rings were a small part of it. The celebration was the rest.
Here’s what the engagement actually cost. The figures come from our proposal story post, which breaks down every dollar:
| What | Cost |
|---|---|
| Private chef (20 servings, engagement party) | $1,769.53 |
| Airbnb celebration (party house with pool and hot tub) | $410.40 |
| Jeweler: 2 engagement rings + 2 wedding rings | $388.00 |
| Dinner in Washington, D.C. (night before proposal day) | $93.11 |
| Lunch in NoVA (friends who helped) | $82.10 |
| Ice skating in NoVA (4 people) | $48.00 |
| Carved, inlaid ring box (handmade) | $37.05 |
| Papersource (handwritten clues and notes) | $27.56 |
| Overnight parking in D.C. | $13.72 |
| Ring size adjuster (temporary — too loose!) | $6.36 |
| Table total | $2,875.83 |
The table totals $2,876, a little more than the $2,535 in our August budget. Some of those costs landed in other categories or other months, and the Airbnb figure here excludes a discount. Add driving (about $30) and beverages (about $200, mostly already at home), and the all-in cost comes to about $3,100. The proposal post puts the true all-in closer to $3,500 once you count the Hyatt points that made the D.C. hotel effectively free (about $250 in value) and the odds and ends.
Either way, the bulk of it went to the celebration, not the rings.
The proposal itself was a 36-hour scavenger hunt across Virginia. The clues led Jenni to people from our past, friends from middle school onward. Sixteen of them were waiting at the final stop to help put the puzzle ring together. Each person held a clue that was a step in reassembling it. I literally couldn’t get engaged without them.
The ring is a custom four-band puzzle ring from a jeweler in Tennessee who has handcrafted each piece for nearly 70 years. Jenni’s four bands stand for friends, family, community, and love. The ring came apart into four loose bands when I was putting it on her finger during the post-engagement celebration. Then, our friends helped put it back together!
We wrote the full story in our engagement series. Start with the benefits of getting married, then the proposal story for the whole breakdown.

FIRE Budget Expense Tracking
Are you interested in tracking your spending as we do? Since 2007, we’ve used Mint to track our credit and bank transactions. It’s where all the numbers in the expense table come from.
Mint is gone now. It shut down in January 2024. The 2023 data here was all tracked in Mint, and Mint data carried into part of 2024 as well. These days, we track across banks with Piere.
Nearly all of our spending is done with rewards-generating credit cards, which makes it easy to digitally track every penny spent (while also earning a bonus).
We’ve made the original Google Spreadsheet available to the public if you’re interested in tracking your annual expenses as we do. You can even make your copy and add your data to it. The spreadsheet is set up for tracking spending between two people, which is then added together. You could easily modify it to work with one person or a family of three or more. You can also download a copy and use your favorite spreadsheet software like Excel or Numbers to make your edits locally.
2016–2023 FIRE Budget
2023 held the line. After a 12% jump in 2022, spending came in flat. Our healthcare costs rose, but travel fell by more. Once we account for inflation, our 2016 spending of $46,966 would be about $60,350 by January 2024 (source: BLS CPI-U). We came in about $3,100 under that, so we’re still doing pretty good. That said, we can’t support many more double-digit year-over-year spending increases. Flat was the right outcome for 2023.
Year-over-year comparison:
| Year | Total Spending ($) |
|---|---|
| 2016 | 46,966.17 |
| 2017 | 44,031.85 |
| 2018 | 42,958.89 |
| 2019 | 40,885.00 |
| 2020 | 40,861.66 |
| 2021 | 51,377.80 |
| 2022 | 57,438.56 |
| 2023 | 57,227.66 |
By the middle of 2020 (and around the time we started TicTocLife), our budgeting goal was just to survive. If we could get out of this pandemic healthy and sane, I don’t think either of us would have batted an eye at a $60K budget. We kept the numbers low in 2020. But 2021–2022 were years of release. We’ve been out traveling and experiencing the world we were shut from for a time. And it’s been well worth it.
Our running average since 2016 is $47,718 nominally. The 2023 figure sits above that average. But the flat year-over-year is what matters. We stopped the climb.
Our 2023 FIRE Number
Our FIRE number for 2023 is $1,430,691.50 — 25 times our spending.
That’s the 4% rule: enough invested that growth pays our expenses, including taxes. We wrote more about this basic tenet in our FIRE introductory post.
| SWR (%) | Required Portfolio Value ($) |
|---|---|
| 4.0 | 1,430,691.50 |
- Withdrawal rate 2.5%. Based on our 2023 spending of $57,227.66 and our December 2023 net worth, our withdrawal rate was around 2.5%. Compare: 2.2% in 2020, 2.4% in 2021, 3.1% in 2022. That’s a meaningful improvement.
- Net worth $2,261,458. Our highest recorded, reached December 31, 2023, while spending stayed flat.
- Savings rate about 52%. New-money saving ($62,335) divided by new income ($119,563). New-money saving is the 401(k), the employer match, the IRA, and the DRIP. That’s money that actually left our hands into investments.
- Checking nets out. Money that flows into Checking and then back out isn’t saving. It’s just delayed spending. Checking shrank by $893 over the year. So the honest rate is 52%, not the 59% you’d get by counting gross Checking inflows as saving.
- December is not a spending spike. The December monthly total looks enormous: $46,630. Almost all of it ($43,200) is year-end savings movement, not spending. The 401(k) contribution, a Checking transfer, and the DRIP all landed in December.
- Still earning, past the income apex. We continue to earn a bit more money through work, though we’re long past the apex of our income. We’ll keep an eye on things, but we’re OK. Our long-term goal is to push extra income into more charitable pursuits like our reader fund. We know how much money is enough for us.
Future FIRE Budget
Our worries about healthcare costs, so far, haven’t proven to be valid. Our move to the ACA has drastically cut our costs as our income has fallen. While healthcare was our most expensive category in recent years, that has changed. Travel costs replaced healthcare as our most expensive FIRE budget item. That feels pretty great.
And 2023 added a new chapter: we’re engaged! Next year will see a wedding to plan, and a budget to match. A FIRE budget doesn’t have to be a restrictive strangle on fun. And we certainly managed to pack a wild ride into our year—one new adventure at a time.
This whole financial freedom thing has come together for us to enjoy life in the way we’ve wanted to. Do you know where to begin to join us? Your very own FIRE budget and plan for financial independence. Let us know if you found some neat tips and tricks to achieving FIRE in our FIRE budget in the comments below.
Monthly sources: the 2023 monthly budget posts
Every number in this post traces back to a monthly budget update. Here they are, month by month:
- January: Dental Gotchas and Saving $1,600
- February: The Cost of Illness & Health
- March: We Missed Our Flight to Madeira!
- April: Our First Full Month in Europe
- May: How We Spent 46 Days in Europe for <$7K
- June: Home, Health, & Hunger
- July: From the Capital to the Coast
- August: Mysterious Personal Gifts
- September: A Month of Iberia Travel Begins!
- October: Portugal, Spain, Azores—30 Days for $4.5K!
- November: Fall in Cancún & Nashville
- December: Desert Holidays & Dividend Christmas

2 replies on “FIRE Budget 2023: Our Life of Financial Freedom on $57,228”
Grace Sophia – Two small things on the annual, both arithmetic, neither a criticism of the method.
1) The 2022 column in the comparison table adds to 54,588.56, not 57,438.56. The 2,850 difference is your 2022 Major Unbudgeted line, which sat outside the parent categories in the 2022 post (Prius upgrade 1,000 plus the HOA garage assessment 1,850). So the column is 2,850 short of its own total. A Major Unbudgeted row for 2022 fixes the arithmetic and leaves the total alone.
2) “46,966 would be about 61,141 by January 2024” is the right number for the wrong month. CPI-U annual 2016 is 240.007 and January 2024 is 308.417, which puts that basket at about 60,350. 61,141 matches roughly March 2024. So 2023 came in about 3,100 under the inflation-adjusted 2016 line, not 3,900. The conclusion holds; it is just less comfortable than the post says.
You mentioned the 2024 and 2025 annuals are in progress. When the 2024 draft exists, I will check the column additions and every inflation-date pairing against CPI before it goes public. That is the part people get wrong and it is the part I am good at.
Grace Sophia
Thanks, Grace! A math helper in the comments doesn’t hurt. 😉 For the 2022/2023 gap, it’s the presentation difference as you said—major unbudgeted didn’t exist moving forward. However, I’ve added it now so that 2022 to 2023 makes a little more sense. This moves the Prius/HOA assessments into major one time expenses for 2022 and similarly, engagement costs move into the same row for 2023. In 2024, the story there will be the wedding costs.
For CPI, annual average is the better choice for the 2016 basis (rather than January’s). Updated, thanks.
And you’re certainly welcome to pop up in the comments once each post is published. Cheers!